
Goals-Based Portfolio Theory Praised as Client Service Guide
Customer photos 1
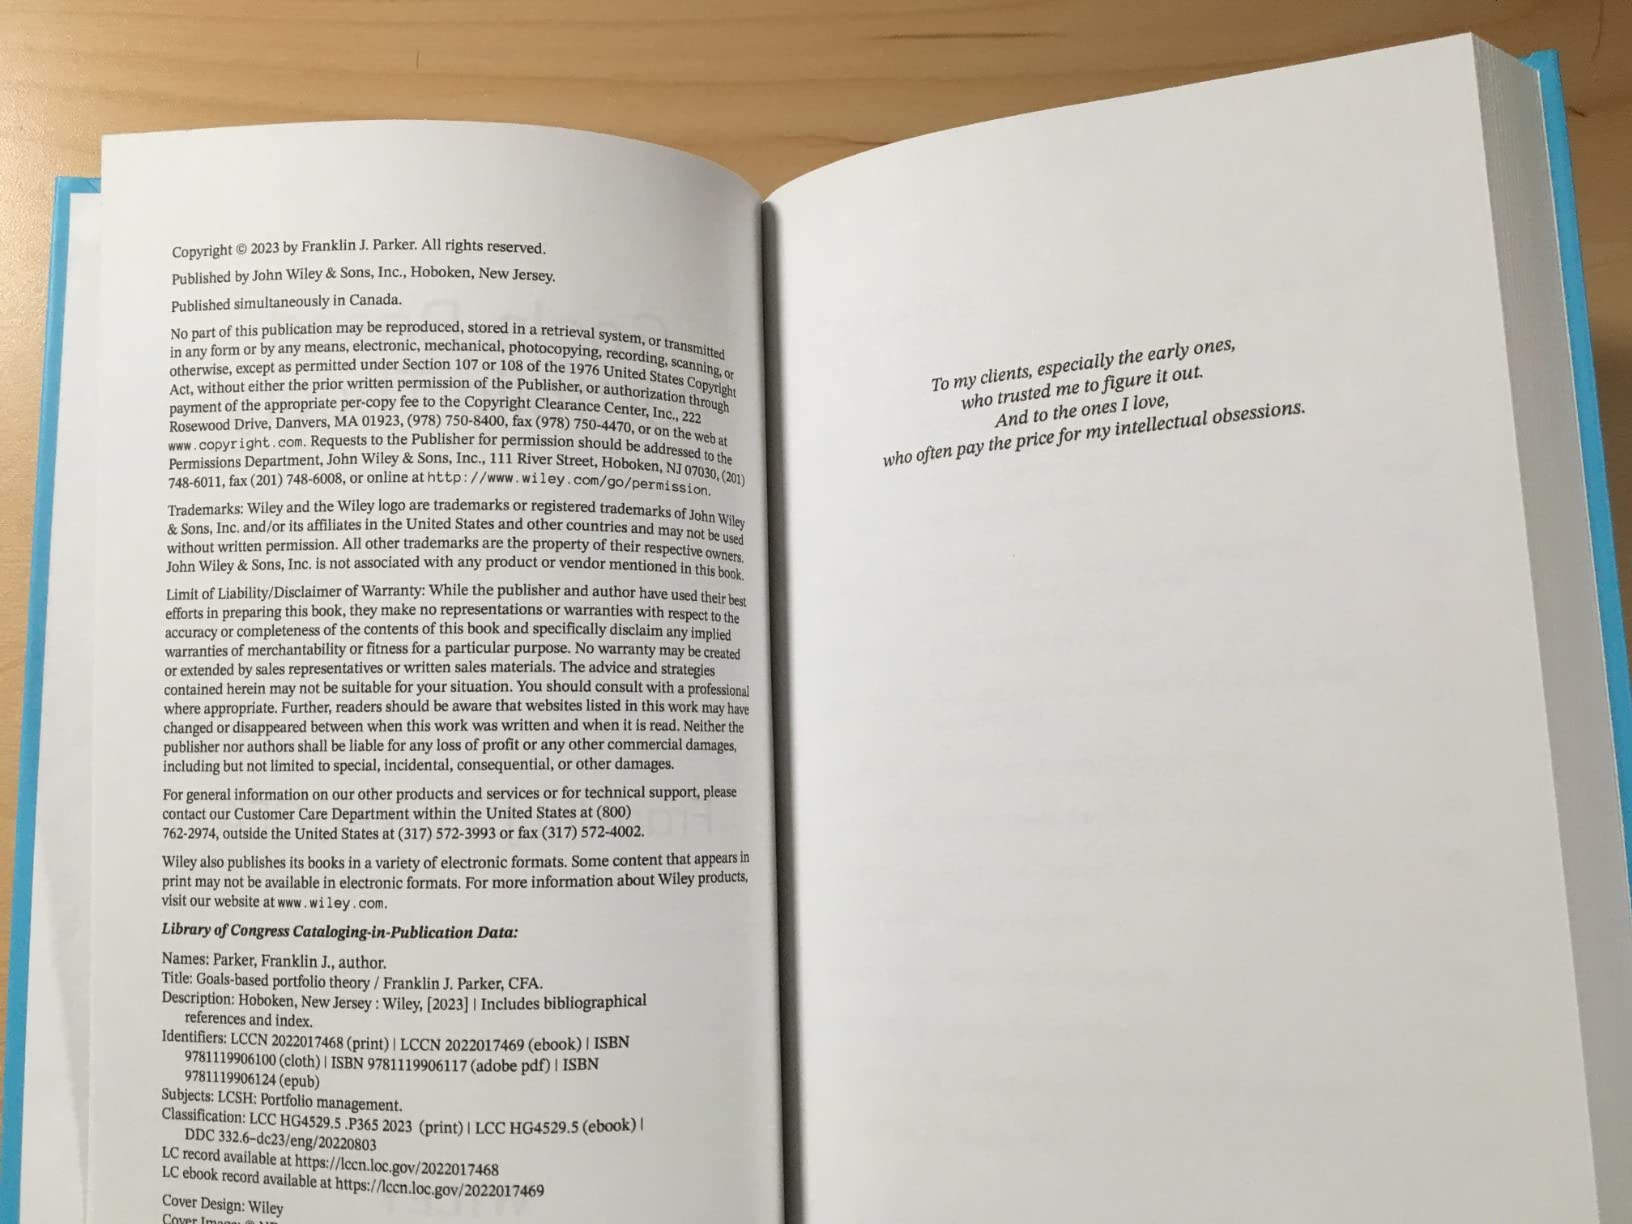
Select a photo to open the gallery.
Full customer review
Customer's headline
A book loved by asset management industry insiders
Franklin eloquently and succinctly highlighted the key tenets of Goals-Based Portfolio Theory, which can be expressed in this analogy: status-quo portfolio management practices are akin to going to a fine restaurant that delivers the same menu to a stream of patrons vs. having a personal chef who caters to the diner's own preferences and *thinks* on behalf of one's patron. Under Franklin's Goals-Based Portfolio Theory, rather than offering selections that doesn't stray far from the core offering, an trusted advisor (which I believe is the wording used in the book) working on behalf of a client would start not by asking "what would you like to have dinner," but to question the premise of whether one should have dinner at all! Perhaps it is better to go for a jog and enjoy a fruit bowl instead! This turns the modern financial advisor-client relationship on its head to lets client goals drive the risk management process (it is not easy to do, and it is very "high-touch"). Most readers familiar to finance would be able to gain valuable perspective from the book, but it would trigger even greater resonance for readers who are already in the asset management industry. On one hand, one might take a view that this book is not specifically catered to bulge bracket traders / "big ten" portfolio managers, since it focuses not on low level asset sectors but instead on precisely and faithfully translate individual clients' goals to portfolio risk exposures. At most dealers and large funds, the risk manager's job is to maximize returns for a large fund company that is in "perpetual existence" - without the Maslow-Brunel Hierarchy of Goals ("dreams," "wishes," wants," "needs") mentioned in the book that applies to individual clients. Yet, on the other hand, most PMs and traders who do meet with clients would recall the "human aspect" of finance that would undoubtedly share some of the Goals-Based objectives even in meeting with an institutional representative (corporate pension officer, for example). This is where the book resonates with me as well. Why not be the PM / the person in charge trading long-end of the curve at a major bank who can sit down and actually talk to the client about how market events and one's outlook / risk exposure may affect the client, rather than sitting down and immediately talking about geopolitics / policy / economy that the client may struggle to connect to actual portfolio outcomes? This is generally where the buyside's portfolio specialist / strategist, and the sell-side sales coverage (sales trader) comes in to root "market talk" back to reality. Yet, for readers of Franklin's Goals-Based Portfolio Theory, there is room for asset allocators to gravitate toward a more approachable figure. Therefore, while the ideal demographic of the book would be portfolio specialists / strategists at large mutual funds who act as a conduit between clients and full-time asset allocators (for the specialists and strategists would perfectly understand all the lingos in the book as well as the supporting formulas), as well as members of a small boutique shop that tailor risk exposure to client needs, it is a good read even for senior risk allocators. The industry might be in a sad state of affair where performance, marketing, and services are weighted 40/30/30, but it illustrates services is still important, and being able to talk to the client like an actual person would still help. If the present industry status quo is client-service 101, Franklin's book is a graduate degree on client service: executive chef working magics at home vs. the status quo of looking at a menu at a restaurant.
 More For A Specialist
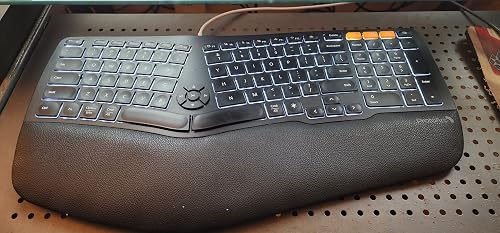 Great Product but needs a couple more Keys
 Great All Around Product
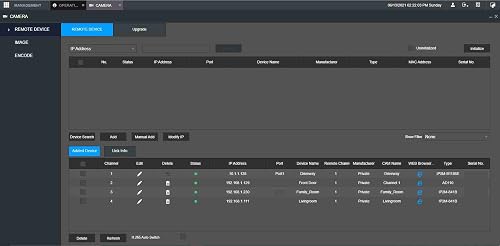 Makes life easy and playback FAST
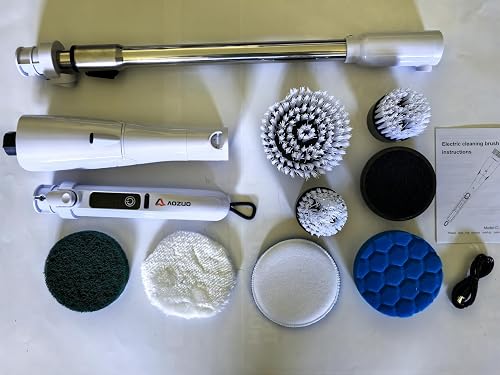 Powerful Cordless Scrubber for Tough Kitchen Grease
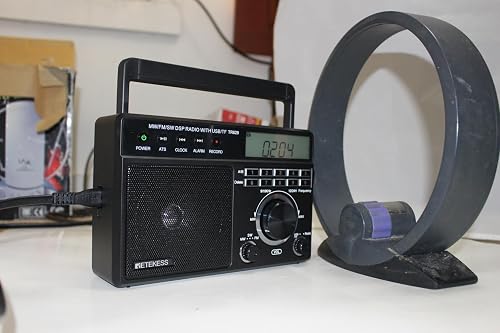 Not a bad mini table radio